Kalyan Jewellers Shares Surge 2.5% Following UBS 'Buy' Rating
Kalyan Jewellers' stock rises after UBS maintains a bullish outlook, projecting significant growth in the upcoming financial quarters.
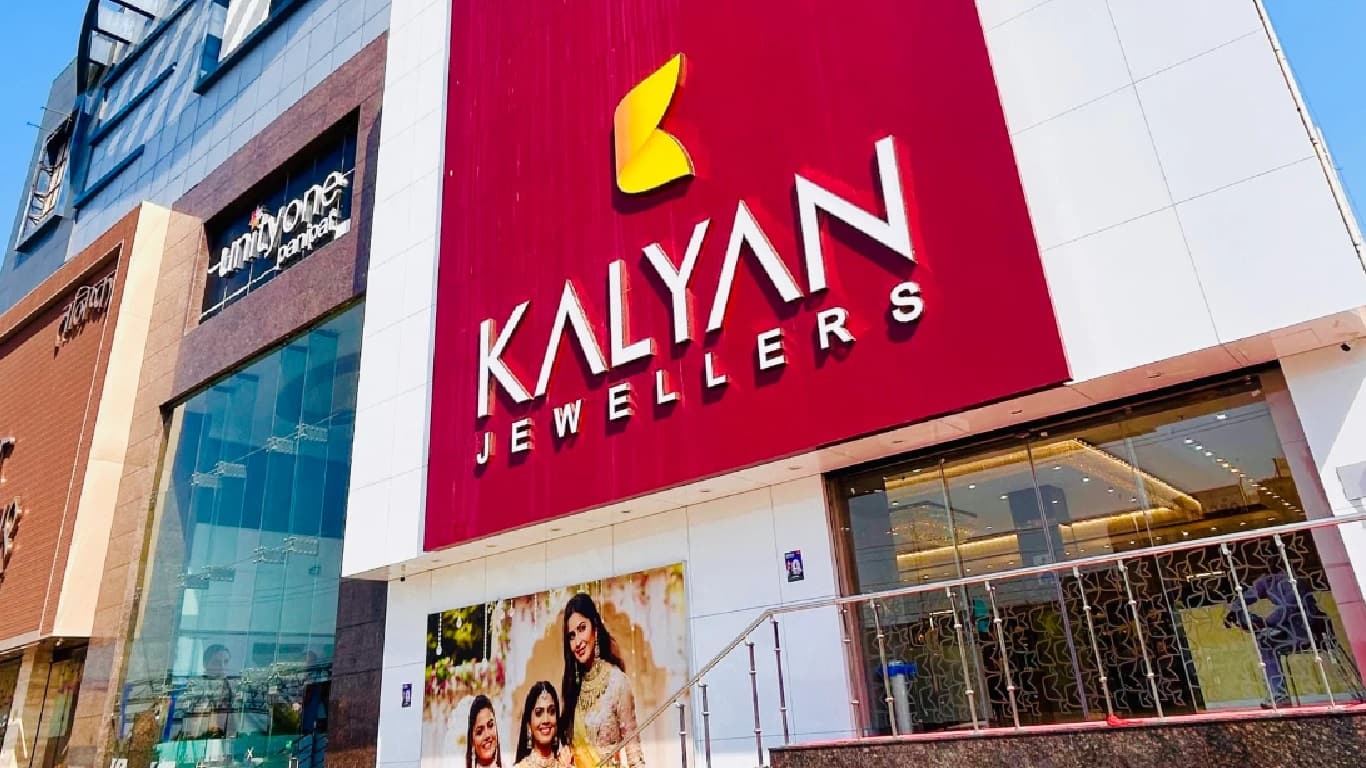
Kalyan Jewellers' shares increased by 2.5% to ₹578, marking a 19% year-to-date rise.
UBS maintains a 'Buy' rating with a target price of ₹900, indicating a potential 60% upside.
The company anticipates strong growth despite high gold prices and plans for aggressive expansion.
Kalyan Jewellers India witnessed a notable increase in its stock price, rising by 2.5% to ₹578 during early trading on Tuesday. This surge positions the company as the leading midcap gainer for the day, following a positive assessment from UBS, which reiterated its optimistic outlook on the jewellery retailer. UBS forecasts robust growth in the latter half of the current financial year, despite the challenges posed by a high base from the previous year.
The stock's recent performance has contributed to an impressive year-to-date gain of approximately 19%. In contrast, the broader market has faced challenges, with the Nifty 50 index declining by 13.3% this year. As of the latest trading session, Kalyan Jewellers holds a market capitalisation of around ₹59,600 crore. The Sensex, meanwhile, was down by 379 points, reflecting a broader market weakness.
UBS has set a target price of ₹900 per share for Kalyan Jewellers, suggesting a potential upside of about 60% from its previous closing price. The brokerage's insights, drawn from discussions with the company's management, indicate a favorable growth trajectory for the second half of the financial year. UBS noted that while elevated gold prices may impact demand and average ticket sizes, Kalyan Jewellers is well-positioned to navigate these challenges.
The firm is also focusing on expanding its store network aggressively, which is expected to drive same-store growth. UBS highlighted the company's gold savings schemes as a strategic advantage, providing better visibility into growth metrics. The brokerage anticipates sustained activity in gold exchange, with Kalyan Jewellers managing the potential impact on profit margins effectively.
Looking ahead, Kalyan Jewellers is expected to continue its expansion strategy, with UBS projecting a compound annual growth rate of around 35% in revenue from FY22 to FY26. The brokerage believes that despite the stock's significant rise in recent years, there remains potential for further re-rating. Kalyan Jewellers reported a 32% year-on-year increase in net profit for the first quarter, reinforcing its strong financial position as it moves forward.